PHOTO
New Zealand has many structural problems; not the least of which is our banking system.
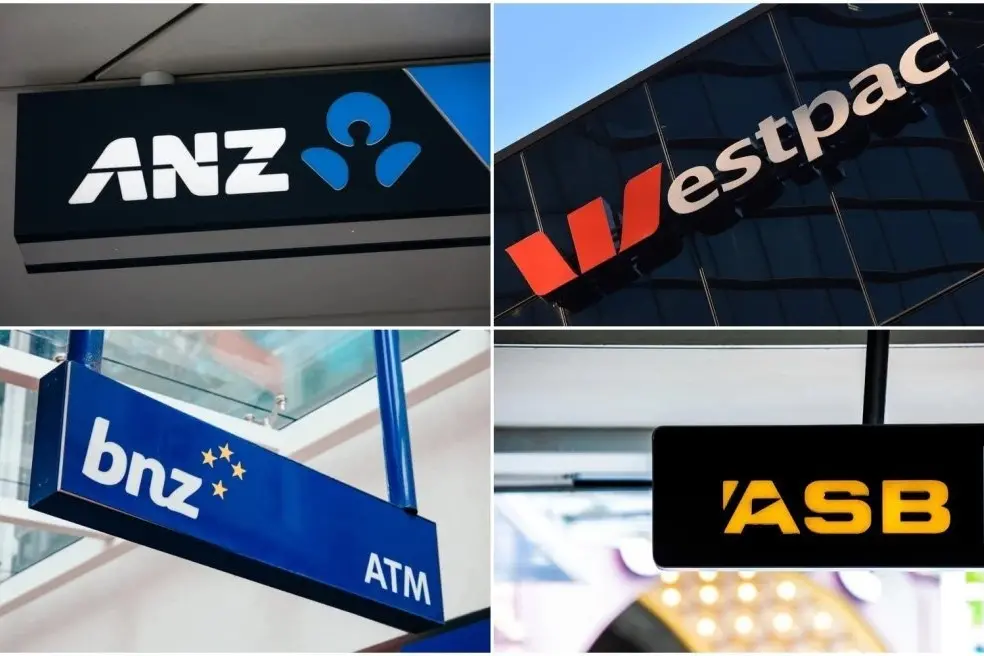
The collective profit of the banks was $7.7 billion for the 2025 calendar year. By way of comparison, the supermarket “excessive profit” is believed to be around $375 million, so which of the two industries has the greater need for an in-depth review?
The banking system worldwide has mastered the art of becoming too big to fail as their governments realise the political blowback of a failure is too immense.
Governments cannot allow any collapse in order to stay in office. The systems they (banks) operate shape this world, yet too often without any degree of social license which most other institutions and industries are compelled to follow.
Size and power, therefore, do matter in the banking world.
Citizens are increasingly detached from governments and councils’ authority, yet the authority granted to the banks ensures they are in control of both givers and receivers – (deposits and loans ) mainly on their own terms which also means their importance to our society is close to absolute.
New Zealand industries such as dairying, which underpin our economy, face growing scrutiny over their biological and environmental impacts — often justifiably.
Meanwhile, banking rules significantly shape the terms under which most other industries operate,
yet banks are rarely held accountable for their decisions.
Reversing the gradual erosion of our social fabric requires real change. A well-functioning banking system should make social cohesion a core part of their financial decision-making.
Banks must assess their contribution to society against growing distrust of both domestic and international banking.
When trust in authorities is lost, self-interest over wellbeing is often the cause. The banking industry must choose whether to strengthen this essential trust or undermine it.
Currently we appear to be in to be in the process of destroying the vital social cohesion needed for our younger members of society who cannot now afford to borrow and mortgage their lives for home ownership. Interest rate anxiety is very real especially for the younger folk who have taken the plunge and are seeking to establish a foothold in society.
If government and banks refuse to recognise this issue, then neither serve the public they purport to serve.
History, however, tells us all there is a way forward.
After World War 2 the government offered rehabilitation loans to returned soldiers at an interest rate of 3% — down to 2% in the first year.
The government home loan was a table loan spanning 25-30 years so that weekly repayments were affordable. Farm loans were also fixed for between 30-40 years to clear debt and develop land.
The need was real for secure loans to be fixed and away from the volatility of the marketplace. It became a time of security and well-being back then, so why not today by requiring banks to offer a government determined fixed percentage of lending, to first home buyers only?
Fixed long term rates are available in the USA/ Noth America and parts of Europe but are unheard of in New Zealand, where a 5-year fixed term and fixed rate are the maximum offered.
Profit making for banks is not just good — it is essential — but therein lies a problem. How much profit is too much profit, given that New Zealand sits second to only to Canada in banking profitability.
Standard and Poors has analysed return on equity of New Zealand banks and found it was at the exceptional level of 12.5%. That wad just three years ago.
Below us in this ranking were Sweden, Australia, Singapore, Finland, Hong Kong and Switzerland.
Canadian banks have large wealth management businesses: our banks don’t. So why is our economy so fragile yet our banks so robust?
While it may be unprofitable for New Zealand banks to offer long term fixed interest rate loans, it is fair to say most industries have unprofitable aspects to their business they would much prefer not to invest in or fund.
If we are to build a future without a gated society, then we need to look hard to find a stable future for our younger members of society who are prepared to work, take risks and to invest.
Not all will of course but the option is needed. Fixed term mortgages offered to first home buyers would become the cornerstone of social cohesion.
Currently the banks are failing the social license test by sticking with their profitable short term volatile interest rates.
All banks should be compelled to set aside a certain percentage of their trading to meet this need.
It would also help if Kiwi Bank joined the Taranaki Savings Bank and Heartland bank proposed merger to better compete with the Australian banks. Two out of three ain’t bad but three out of three is needed.
So what about the disaster of Fannie May and Freddie Mac in the US I hear you say?
Fannie and Freddie are government-sponsored enterprises which bought residential mortgages on the secondary market to hold or sell off to pension funds.
They also bought mortgages from private lenders who in turn used that cash to extend more loans to those who could ill afford to borrow. Such loans were distressed in no time so when the first domino fell – near total collapse followed.
Our banks absolutely need to be profitable and still meet the needs of the wider community. In The History of Freedom Lord Acton wrote: ``the struggle of modern civilisation would inevitably boil down to the people versus the banks.’’
As a country we need to talk about this.
- Gerrard Eckhoff is a former Otago regional councillor and Act New Zealand MP.