PHOTO
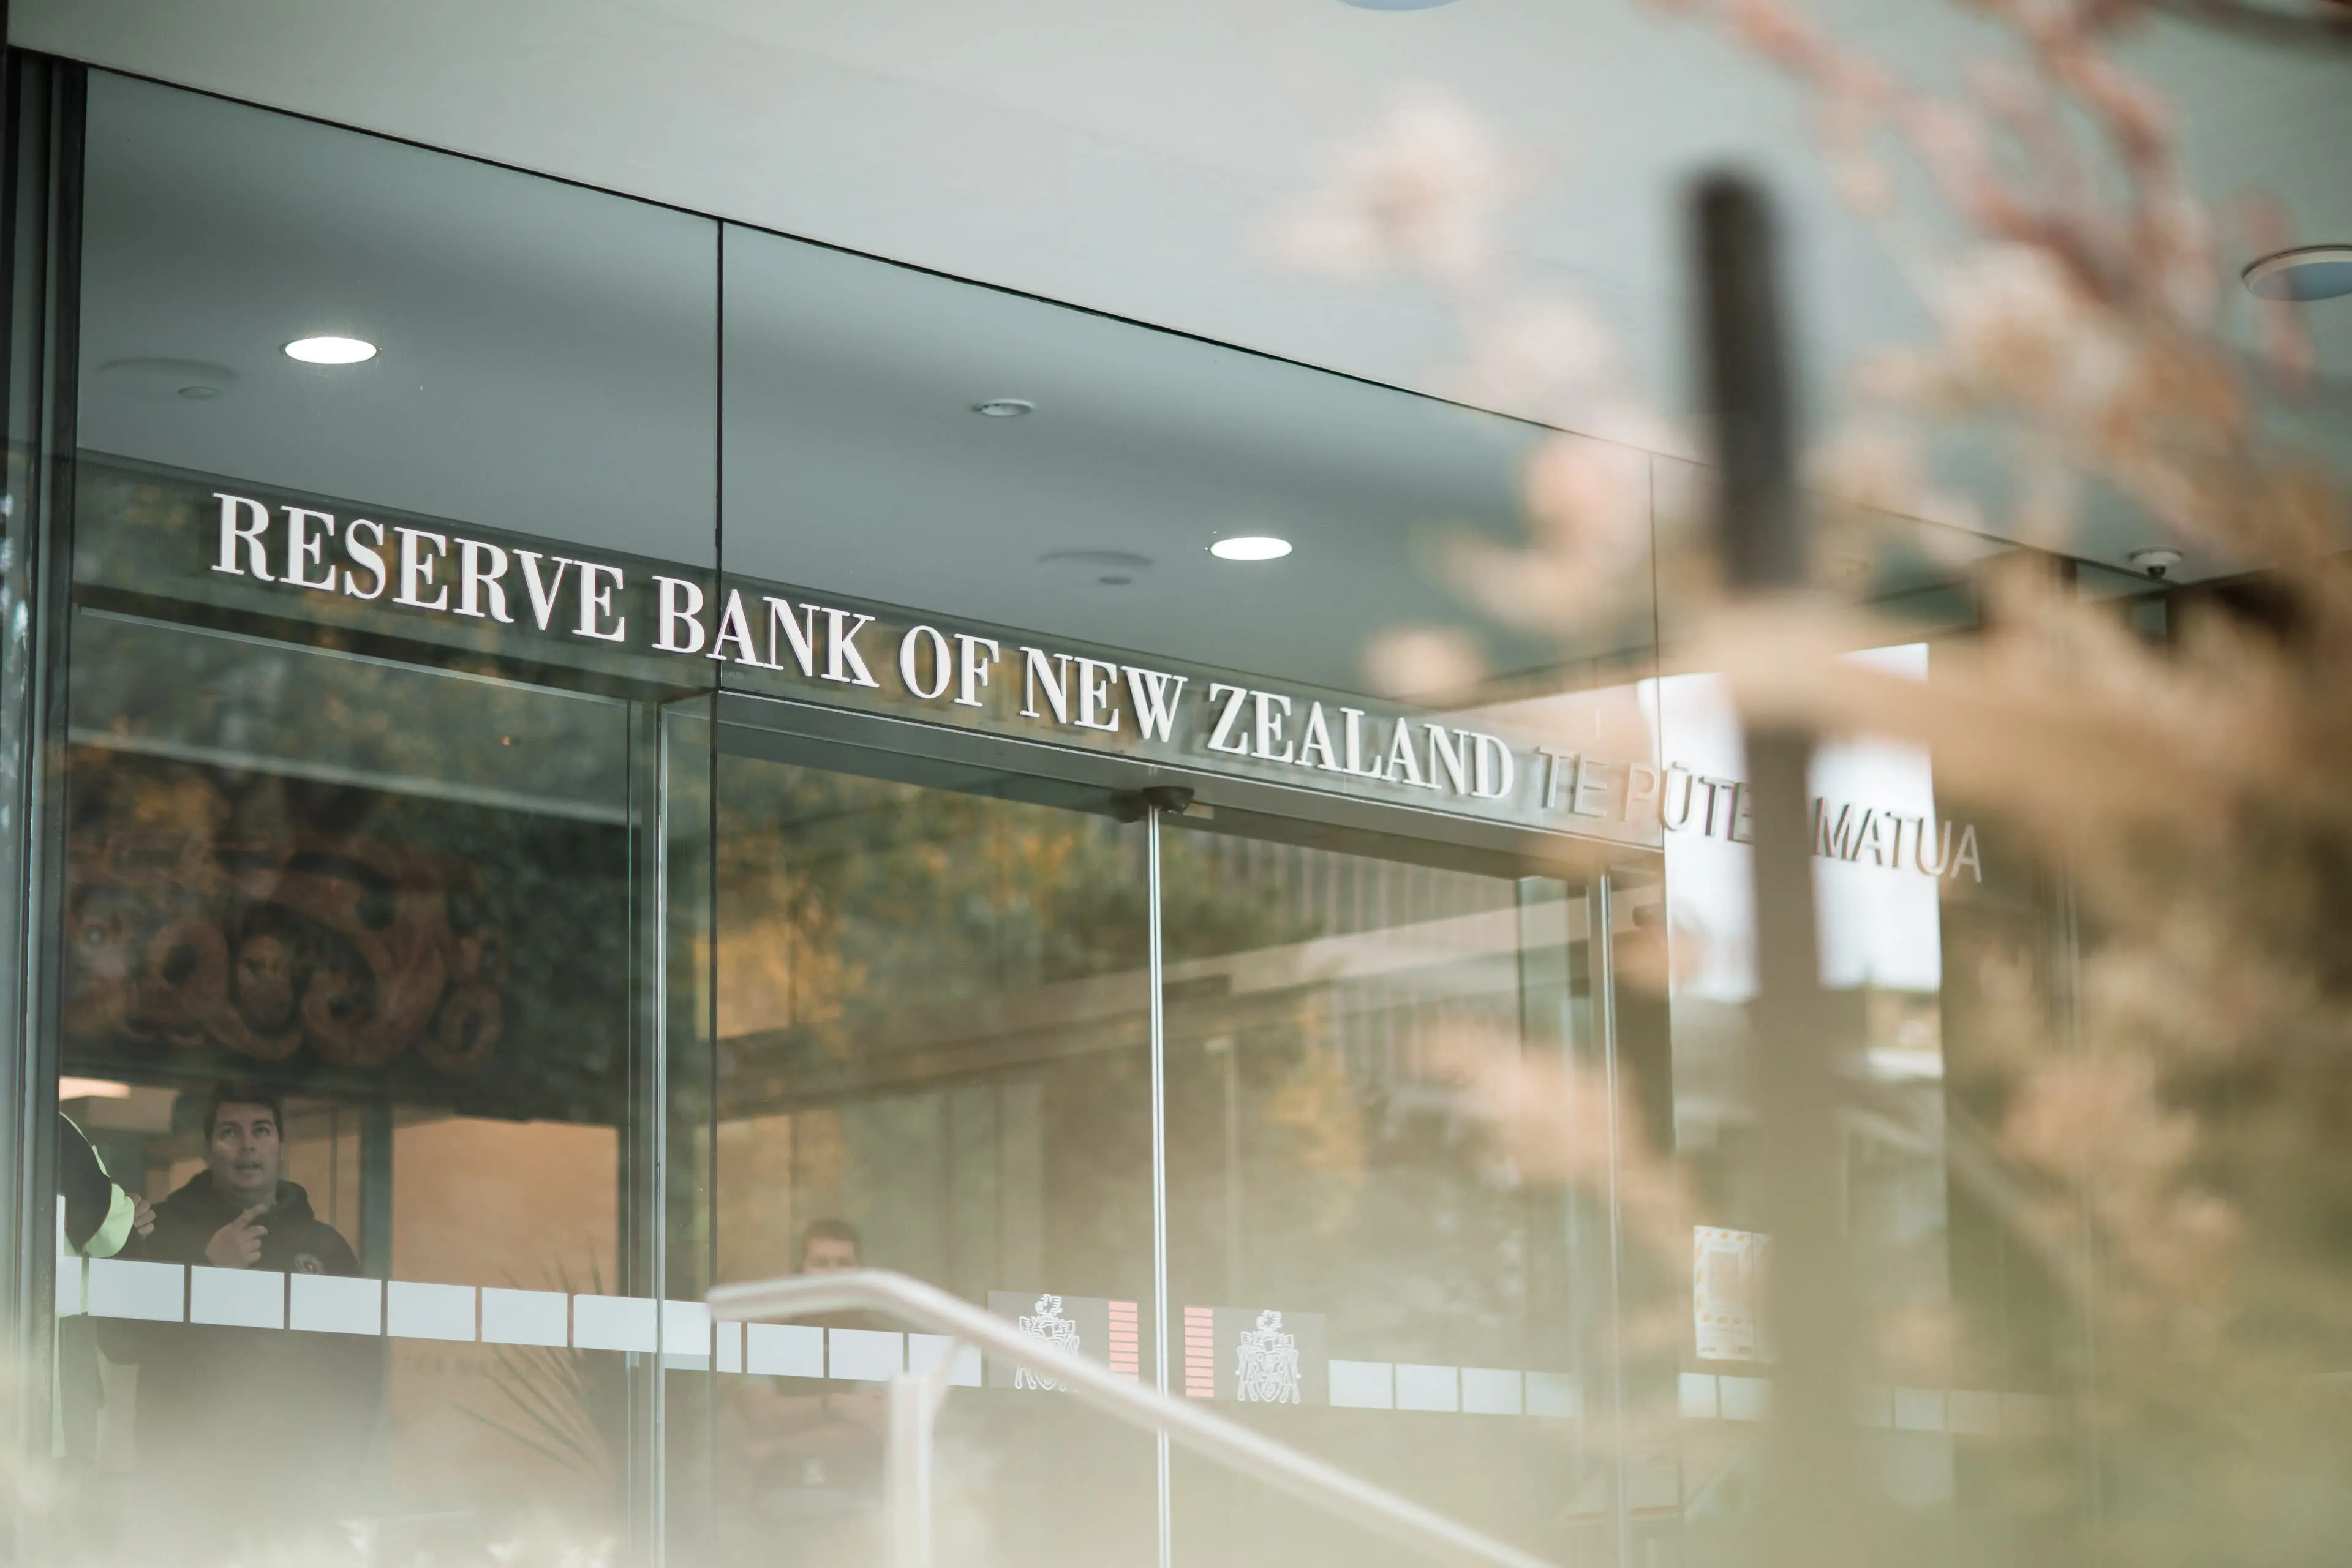
The Reserve Bank's response to the Covid-19 started well, but went on much too long.
That is the finding of an independent review which was released by the Government on Tuesday.
The review was conducted by Massachusetts Institute of Technology Professor Athanasios Orphanides and former Reserve Bank Assistant Governor David Archer and examined the decisions made by the Reserve Bank's monetary policy committee (MPC), and the analysis around those decisions.
It said the initial response was appropriate.
"The Covid epidemic threw up huge challenges. MPC's initial response was praiseworthy; rapid and, for New Zealand, innovative monetary accommodation was provided. The early adoption of a Least Regrets strategy helped get ahead of the potential for a compounding collapse and the quick rollout of Large Scale Asset Purchases (LSAPs) prevented market dysfunction from becoming part of the problem. Alongside an equally impressive fiscal response, Bank policy actions gave the New Zealand economy a timely and much-needed boost," the report said.
It said reducing interest rates helped reduce the risk of a severe downturn. The official cash rate (OCR) was slashed to 0.25 percent and the Reserve Bank started to use other methods to get more money into the economy, such as large-scale asset purchases, which the report said helped restore the functioning of government bond markets, and the funding for lending programme.
But the report said the monetary stimulus remained in place too long.
The economy recovered more strongly than expected and policy did not adjust quickly enough. The continued stimulus combined with that recovery meant there was excess demand in the economy and inflation increased significantly.
The report said it took a full year for policy to adjust to the reality that the initial economic stimulus had already achieved the intended result.
It said data that was more positive than expected was discounted and risks that inflation would go too high were downplayed. That meant, when the Reserve Bank did take action on inflation, interest rates had to go higher, which led to weaker economic growth and higher unemployment.
"As inflation accelerated away from target, MPC decided to stop adding stimulus, but without sufficient urgency. The real policy interest rate - rarely discussed in MPC communications -continued to decline, and reached historic lows, even after the MPC communicated withdrawal of stimulus and hikes in the nominal Official Cash Rate (OCR). As a result, the economy overheated to an historically extreme degree. Inflation rose as far as 7.3 percent, 5.3 percent above target, and the unemployment rate fell to 3.2 percent, an unsustainable historic low, necessitating a costly reduction in economic growth and employment to restore stability."
It said the decision-making approach was vulnerable to uncertainty, relied too much on forecasts showing inflation returning to target and gave insufficient weight to incoming data, near-term inflation, falling unemployment, real interest rates, and the risk that inflation would remain high."
It said New Zealand was also not ready to use the full range of tools when the OCR approached its lowest practical level.
"Negative Interest Rate Policy (NIRP), a powerful and flexible tool, was inexplicably not ready for implementation. Some new policy tools were, later, rushed into action with insufficient forethought."
The report made recommendations for the Reserve Bank including that it should develop a framework to make better decisions under uncertainty, with a a clearer and more systematic strategy, test a wider range of scenarios, and use simple benchmarks to check policy decisions.
It should give attention to current conditions: give more weight to real interest rates, near-term inflation and incoming economic data.
It said it should regularly review and test additional monetary policy tools so they are ready when needed, and encourage different perspectives, strengthen voting and public transparency, and provide sufficient economic research and analysis for MPC members.
It said the Government should revaluate sections of the Reserve Bank Act that concern the balance between the MPC's ability implement monetary policy, including through tools that may create financial risk, and the responsibilities of the Reserve Bank Board and the Minister of Finance for managing risks to the Reserve Bank and the Crown.
Finance minister Nicola Willis said the reviewers also took issue with the previous government's decision to broaden the Reserve Bank's mandate by requiring it to support maximum sustainable employment as well as maintain price stability.
"In the reviewers' words 'these amendments downplayed the importance of price stability' and 'effectively mandated that the Bank should tolerate larger and longer lasting inflation deviations from target'.
"One of this Government's first actions on taking office was to restore the Bank's single focus on inflation, as the greatest contribution monetary policy can make to employment in the medium term is keeping inflation under control," she said.
"The reviewers also welcomed changes made to the MPC charter earlier this year to encourage diversity of thought in MPC decision-making.
"Those changes include making committee members' votes public when there is not consensus and making it easier for MPC members to discuss their views publicly."
Willis said she expected the bank to consider the review's recommendations carefully and report publicly on its response.
"The Government also acknowledges the review's recommendations around the interaction between financial governance and monetary policy and will consider further advice.
"The Covid-19 pandemic constituted an unprecedented economic shock. It has taught New Zealand some painful lessons.
"It is important that we learn those lessons and do not repeat the mistakes of the past," she said.